What to expect before, during and after a scope 3 assurance engagement
Auditors do not expect perfect data. They want to see a clear, transparent and well-documented approach. Scope 3 assurance is a valuable opportunity to strengthen controls, improve data quality and build confidence in future reporting.
In this webinar, Katharina Bauch, Head of Carbon at thinkstep-anz, is joined by Mark Crichton, Sustainability Program Advisor AUNZ, and Rhea Selwan, Lead Auditor and Sustainability Advisor at SGS.
Together, they explain what happens during a scope 3 assurance engagement, what evidence auditors look for and how to prepare. They also unpack common assurance terms and share practical ways to improve your scope 3 data over time.
Watch the webinar replay here or scroll down for five key takeaways and Q&A with our speakers.
Five key takeaways
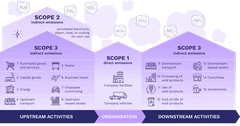
1. Estimate all relevant scope 3 categories
Do not exclude a category because the data is difficult to collect. Start with a reasonable estimate, then investigate further if it is significant.
2. Focus on material emissions
Use estimates to identify your emissions hot spots. Improve data quality where emissions are highest and keep lower-impact categories simple.
3. Show how you reached the number
Document your methods, sources, emission factors, assumptions and calculations. Auditors need to trace each figure back to its source.
4. Auditors focus on risk
Auditors consider the size of each emissions source, the uncertainty involved and the potential for errors. These risks determine where they test more closely.
5. Understand the assurance process
Limited assurance involves less testing than reasonable assurance. Engage your assurance provider early to agree on the scope, evidence and level of assurance needed.
Q&A with Mark, Rhea & Katharina
Do auditors have a set structure for limited vs reasonable assurance? Or is the approach for each based on the assurers’ own approach?
There is a set structure for auditors to follow when it comes to limited vs reasonable assurance, as laid out by New Zealand’s External Reporting Board (XRB). The auditor will apply this structure to their review, as well as their own experiences, which help them understand where to draw the line for a limited vs reasonable assurance audit activity. For a clear definition of limited vs reasonable assurance, please refer to ISO 14064 part 3.
Is there an audit average amount/percentage of data that should be investigated (verified) in both a limited and reasonable assurance process?
Auditors set a materiality threshold which changes depending on the level of assurance required. A 5% threshold applies for reasonable assurance, while a higher threshold up to 10% may apply for limited assurance.
Under Australian regulations, are there any specific data quality requirements for Scope 3 emissions? This is particularly relevant because collecting reliable data for upstream Scope 3 emissions can be challenging due to limited supplier-specific information, inconsistent reporting methods and reliance on secondary data or estimates.
The data quality requirements for scope 3 emissions are listed in paragraph B40 of the Australian Sustainability Reporting Standard (ASRS) AASB S2 for Climate-related Disclosures.
Are the emission factors already verified to be of good quality, given they come from different sources like national and international databases? Are users allowed to use EFs from any source?
Emission factors from known databases, such as those from the Australian and New Zealand governments, are usually considered good quality. These two databases in particular do not require further verification. However, bespoke emission factors will need to be checked to see if they have been third-party verified. If not, further investigation is required – this will take additional time which should be included in the scope of the audit. On top of this, auditors will also need to check that the most up-to-date emission factors have been used.
In the example of using supplier-specific data from an EPD, where would the construction company get the GWP emission factor from, specifically? Is it the total sum across all modules A-D?
Let’s assume the construction company is the one buying the materials. They should use stages A1–A3, which cover the materials from the factory (cradle-to-gate). Then there is stage A4, the transport to the building site. If the company organises the transport themselves, they will have the best data. If they don't, they can use the transport information included in the material’s EPD (if they include it).
When referring to documentation, are there guides or examples of the different approaches how data can be managed and reported – like defining reporting boundaries, etc?
For standard documentation and guidance, you can refer to the GHG Protocol standard. For more bespoke guidance, you can engage your local sustainability professional to help prepare you for reporting your data. Find out more about thinkstep-anz’s carbon services and talk to our experts today!